Teaching
I have taught probability, statistics, calculus, and financial mathematics since 2012, at the undergraduate and graduate level. In January 2026 the University of New Haven named me to the Whitley Professorship in Mathematics and Physics, for teaching.
Courses
University of New Haven, 2025 to present
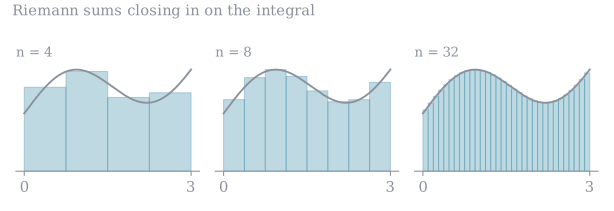
- MATH 1117 · Calculus I. Fall 2025, Spring 2026, Fall 2026. New preparation; the spring redesign runs on standing groups, split individual and collaborative quizzes, and calculus animations built in Manim.
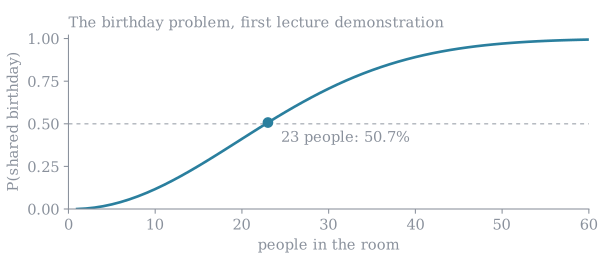
- MATH 3371 · Probability and Statistics I. Fall 2025. Aligned to the SOA Exam P syllabus; Python demonstrations in lecture; students choose between an Exam P format final and a modeling project.
- MATH 4472 · Probability and Statistics II. Spring 2026. Assessed through an applied project on a dataset from each student's own field and an oral exam.
Earlier
- Worcester Polytechnic Institute (2024 to 2025). Multivariate Calculus; Probability and Applications.
- UC Santa Barbara (2021 to 2024). Probability and Statistics I and II; Regression Analysis, built around a term-long project in R; Applied Stochastic Processes, with live Python coding for Markov chains and Monte Carlo option pricing; Mathematics of Fixed Income Markets, on the SOA FM syllabus; Actuarial Exam Tutorial, whose syllabus I wrote from the SOA curriculum.
- Evry University, France (2012 to 2016). Financial instruments and derivatives pricing, Master of Financial Engineering program.
Actuarial program
- Coordinator of the B.S. in Actuarial and Mathematical Sciences at the University of New Haven.
- Led the UCAP-IC recognition application to the Society of Actuaries. Granted.
- Led the Bronze recognition application to the Casualty Actuarial Society. Granted, extending the program into property and casualty.
- Wrote the SOA Exam P alignment documentation for MATH 3371 and the curriculum pathway to the SOA preliminary exams.
- Department liaison to insurance employers in Hartford, Stamford, and New York, through the Corporate Partnership Council.
- Designed a graduate elective, Volatility Modeling and Derivatives Pricing, built around Python projects and market case studies.
Mentoring
- University of New Haven. Supervising an undergraduate honors project on climate risk and insurance premium pricing in Connecticut.
- UC Santa Barbara. Committee member of the CFMAR Undergraduate Lab, selecting students and pairing them with mentors for two-quarter research projects; mentored lab students and an honors project.
- UC Berkeley. Mentored students on their seminar projects at the Consortium for Data Analytics in Risk.
- Pierre and Marie Curie University / AXA. Supervised a graduate intern from the Master of Financial Mathematics through a six-month project; we co-authored a paper, and she went on to a Ph.D.